

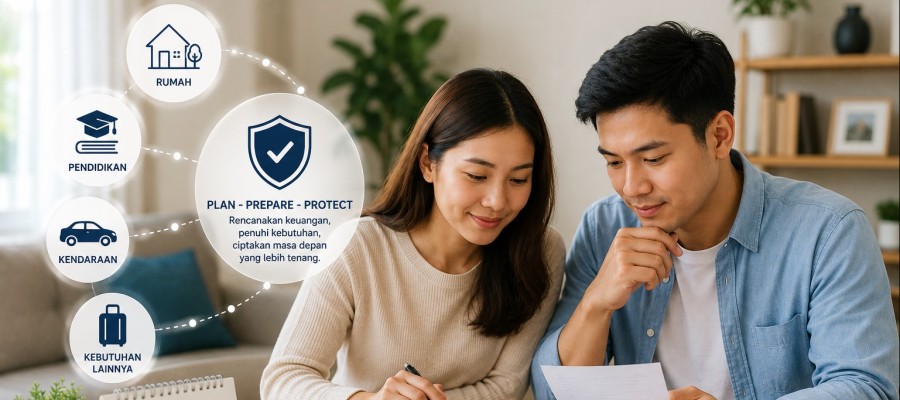


Major expenses, such as a vehicle, education, or important family needs, often require careful planning. Financing may be one option, but the decision should not be based solely on how much money is available to borrow. The key is making sure repayments remain within your financial capacity.
Consider these steps before applying for financing:
Calculate your regular income, essential expenses, bills, and existing installments. This helps you estimate how much you can realistically allocate to a new repayment.
Separate essential needs from wants that can wait. Make sure the financing serves a clear purpose and fits your financial goals.
Do not focus only on the amount you can obtain. Consider whether you can make regular payments without compromising everyday needs or other obligations.
Review the installment amount, repayment period, any down payment, interest or margin, administration fees, late-payment charges, and the agreement’s conditions. OJK advises consumers to understand their rights, obligations, and all costs related to financing products.
Avoid using all your remaining income for installments. Set aside money for daily needs and emergency expenses to preserve financial flexibility.
Seek information from official financing providers, compare costs and terms, and ask questions about anything unclear. Choose an option that fits your needs and repayment capacity, not merely the one with the fastest process.
OJK emphasizes that using financial services should be accompanied by an understanding of risks and the ability to meet obligations. The same principle applies when considering financing: assess repayment capacity realistically, understand the agreement, and avoid commitments that could undermine financial stability.
Source: Ojk.go.id
<< Back